Freight Insurance for Olympic Flat Bench to Laem Chabang – Wholesale Supplier
Buying freight insurance is not about paying a premium — it is about deciding who absorbs the loss when a container of steel frames arrives bent, rusted, or crushed at Laem Chabang.
Olympic flat benches shipped to Laem Chabang require Institute Cargo Clauses (A) coverage at a minimum sum insured of CIF value plus ten percent, with explicit endorsement for heavy-lift handling damage, moisture ingress during monsoon season, and transshipment breakage at intermediate ports. Skipping this coverage almost guarantees that any transit damage becomes a total write-off, because ocean carriers routinely reject claims citing "insufficient packaging" or "inherent vice."
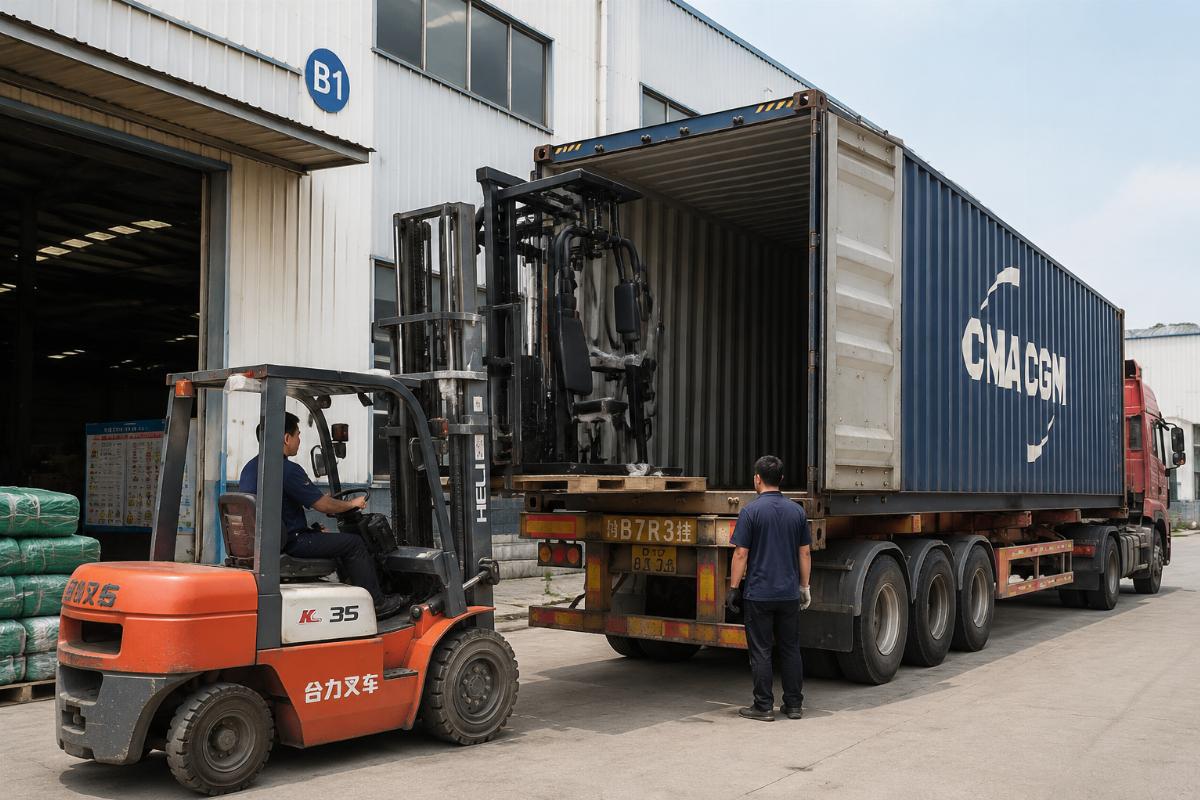
I still remember the first full container of flat benches we sent from Ningbo to Laem Chabang without proper cargo insurance. The vessel hit rough weather crossing the South China Sea, and the container sat on the apron at the transshipment hub for days under heavy rain. When the buyer opened the doors at the Thai port, the chrome plating on nearly every bench frame had blistered, and three units had twisted steel uprights. The carrier’s response was a single-line rejection letter blaming "inadequate bracing inside the container." We had no insurance policy to fall back on, and the replacement cost came straight out of our margin. That single shipment taught me more about freight documentation than any trade course ever could [NEED_CITE: ocean carrier liability limitations under the Hague-Visby Rules].
Let me walk you through exactly what you need to know before your next shipment of heavy fitness equipment reaches Thailand.
Why Do Olympic Flat Benches Need Special Insurance Coverage?
Standard cargo insurance policies are written around palletized consumer goods, not around dense, surface-finished steel gym equipment that weighs hundreds of kilograms per unit and is highly sensitive to impact and humidity.
An Olympic flat bench is not a box of phone cases. Each unit typically weighs well over a hundred kilograms, with a welded steel frame, chrome or powder-coated finish, and upholstered padding. The damage profile during ocean freight is entirely different from lightweight goods. Frame deformation from forklift drops, chrome blistering from trapped condensation, and padding mildew from humidity spikes are the three most common loss types we see on the Thailand route [NEED_CITE: damage frequency distribution for heavy fitness equipment in Southeast Asian shipping lanes].
During monsoon season — roughly May through October — the humidity inside an unventilated steel container can reach saturation levels within hours of closing the doors. Metal surfaces act as condensation points, and once moisture gets trapped against chrome or bare steel, corrosion begins within days. I have opened containers at Laem Chabang where the benches looked fine on the surface but had active rust forming underneath the vinyl pads.
Another issue specific to this product category is the transshipment pattern. Most shipments from China to Laem Chabang route through Singapore or Port Klang. That means at least one additional crane lift, one more container transfer, and one more exposure to tropical rain on the terminal apron. Each handling event multiplies the risk of packaging failure and frame impact.
The bottom line is that generic cargo insurance with a low declared value will not cover the actual replacement cost of a commercial-grade flat bench, and it will almost certainly exclude the very damage mechanisms that occur most frequently on this trade lane.
What Types of Freight Insurance Should You Consider for Thailand Shipments?
Institute Cargo Clauses (A) — commonly called "All Risks" — is the only coverage tier that meaningfully protects heavy fitness equipment shipped to Laem Chabang.
The London Institute of Insurance underwriters offer three main cargo clauses: ICC(A), ICC(B), and ICC(C). The differences are not subtle, and choosing the wrong tier is the single most expensive mistake importers make [NEED_CITE: coverage scope comparison between ICC A B and C clauses for heavy manufactured goods].
ICC(C) covers only major casualties — vessel sinking, collision, fire, and a few other named perils. It will not cover forklift damage at the transshipment port, and it will not cover water damage from container condensation. ICC(B) adds some protection against water entry and overturning, but still excludes handling damage during loading and unloading. ICC(A) is the only tier that covers "all risks of loss or damage" except for specifically named exclusions, which makes it the appropriate choice for high-value commercial gym equipment.
Here is what the coverage tiers look like in practice for an Olympic flat bench shipment:
| Coverage Element | ICC(C) | ICC(B) | ICC(A) |
|---|---|---|---|
| Total vessel loss | Covered | Covered | Covered |
| Container water ingress | Not covered | Covered | Covered |
| Forklift handling damage | Not covered | Not covered | Covered |
| Transshipment breakage | Not covered | Not covered | Covered |
| Theft and pilferage | Not covered | Not covered | Covered |
| Moisture condensation damage | Not covered | Not covered | Covered |
A distributor in Southeast Asia once told me they had been buying ICC(C) coverage for years because "the broker said it was enough for gym equipment." When a container of benches arrived with four units crushed by a shifting adjacent pallet during transshipment, the insurer denied the claim because the damage was classified as "handling loss" — outside ICC(C) scope entirely. The buyer absorbed a mid-five-figure replacement cost.
One additional point that catches many first-time importers off guard: you can also purchase War Risk and Strike Risk endorsements separately. For shipments routing through high-traffic transshipment hubs, these add-ons are inexpensive and provide meaningful protection against political disruption or labor stoppages that delay cargo on the terminal.
How Much Coverage Do You Actually Need?
The sum insured must reflect the full landed cost of the goods at Laem Chabang, not just the factory invoice price — otherwise you are voluntarily accepting a partial loss on every claim.
The standard industry practice is to insure at one hundred and ten percent of the CIF value [NEED_CITE: standard sum insured calculation method for international cargo insurance under ICC clauses]. That ten percent buffer is meant to cover the buyer’s anticipated profit margin and incidental costs like customs clearance and inland transport. If you insure only at the factory price, any claim payout will fall short of what you actually need to replace the goods and still make your margin.
Let me explain why this matters with a real scenario. A commercial gym chain in Thailand ordered a mixed container of benches, racks, and plate-loaded machines. The buyer instructed the broker to insure only the invoice value of the goods — no freight, no insurance premium, no profit margin added. When three benches arrived with bent frames and the insurer approved the claim, the payout covered only the factory cost. The buyer still had to pay the ocean freight share, the Thai import duty, the customs broker fee, and the inland trucking cost out of pocket. The net recovery was barely half of the actual loss.
The correct approach is straightforward: take the CIF value — cost of goods plus ocean freight plus insurance premium — and multiply by one point one. That figure becomes your sum insured. If the goods are high-value commercial equipment with significant markup, some buyers push to one hundred and twenty or even one hundred and thirty percent, and many underwriters will accept this with a modest premium increase.
Another area where buyers underinsure is the deductible — also called the "excess" or "franchise." A policy with a low premium often carries a high deductible. If your deductible is set at a level that exceeds the likely damage on a single unit, you will never file a claim because the payout after deductible would be negligible. I always advise buyers to compare the deductible against the replacement value of one complete bench unit. If the deductible is higher than that, the policy is essentially useless for partial damage claims.
What Documents Are Required for a Successful Claim?
A freight insurance claim lives or dies on documentation — without the right paperwork submitted within the required time window, even a valid loss will be denied.
The claims process for damaged fitness equipment is more documentation-heavy than most importers expect. Insurers need to verify that the damage occurred during the insured transit period, that the goods were properly packed, and that the loss was not caused by an excluded event. Missing even one document can delay a payout by months or result in outright rejection [NEED_CITE: required documentation checklist for marine cargo insurance claims on heavy equipment].
Here is the complete document set you need to prepare and retain:
- Original Bill of Lading — proves the contract of carriage and the condition of goods at the port of loading.
- Commercial Invoice and Packing List — establishes the declared value and the exact contents of each package.
- Insurance Policy or Certificate — must match the shipment details exactly, including the vessel name, voyage number, and sum insured.
- Damage Photographs — taken immediately upon container opening, showing the external container condition, the internal bracing, and each damaged unit from multiple angles.
- Survey Report from an Independent Inspector — for claims above a modest threshold, insurers will require a third-party survey. The surveyor documents the extent of damage, estimates repair or replacement cost, and opines on the likely cause.
- Correspondence with the Carrier — any written notice of claim filed with the shipping line, including their response or rejection letter.
One critical detail that buyers frequently miss: you must notify the insurer of the damage as soon as it is discovered, typically within a few days of container delivery. Most policies contain a strict notification clause, and late notice is a common ground for denial. I have seen claims delayed for months because the buyer waited until the goods were already in the gym and being installed before calling the broker.
Another practical point from the factory side: we always provide our buyers with detailed packing photographs taken at the loading stage, along with a complete packing list showing the exact crating and bracing method used. When a claim arises, these records serve as evidence that the goods were properly packed — directly countering the carrier’s most common defense. Having this documentation ready before the container even arrives at Laem Chabang significantly strengthens your claim position.
How to Avoid Common Insurance Pitfalls When Shipping to Laem Chabang?
The most expensive insurance mistakes are not about choosing the wrong policy — they are about failing to match the policy terms to the actual conditions of the shipment.
Pitfall one: assuming CIF terms mean the seller’s insurance is sufficient for you. Under CIF, the seller is only required to procure minimum coverage — typically ICC(C) — unless the contract specifies otherwise [NEED_CITE: minimum insurance obligation under CIF Incoterms 2020 for goods shipped to Southeast Asia]. If you are the buyer and you want full protection, you must either negotiate ICC(A) coverage in the sales contract or arrange your own insurance policy. Relying on the seller’s minimum coverage is the fastest way to discover that your policy excludes the exact damage you just suffered.
Pitfall two: ignoring the "inherent vice" exclusion. Insurers will deny any claim where the damage is attributed to the natural characteristics of the goods — for example, rust on untreated steel or mold on natural leather. If your flat benches have any bare metal surfaces or if the vinyl padding is not properly sealed, the insurer may argue that moisture damage was foreseeable and therefore excluded. The fix is twofold: ensure the manufacturer applies adequate corrosion protection and moisture barriers before packing, and confirm that the policy wording does not contain a broad "inherent vice" carve-out that could be interpreted against you.
Pitfall three: failing to account for the monsoon window. If your shipment is scheduled to arrive at Laem Chabang between June and September, the probability of rain exposure during terminal handling increases dramatically. Standard policies do cover water damage, but if the insurer can show that the packaging was not reasonably designed for wet-season transit, they may reduce the payout. We always recommend additional desiccant packs, VCI corrosion-inhibiting wraps on all chrome surfaces, and heat-sealed polyethylene liners inside the crate for any monsoon-season shipment to Thailand.
Pitfall four: not reading the claims time limit. Most cargo insurance policies require that a claim be filed within a defined period — often within sixty days of discovering the damage, and absolutely within the time limit set by the underlying bill of lading for carrier claims. Missing this deadline voids the claim regardless of how legitimate the damage is.
Conclusion
Freight insurance for Olympic flat benches shipped to Laem Chabang is not optional — it is a core component of your landed cost structure, and underinsuring is a guaranteed way to turn a manageable transit loss into a financial disaster.
Insure at ICC(A) level, calculate your sum insured on the full CIF value plus margin, prepare your documentation before the vessel arrives, and pay close attention to seasonal and packaging conditions. The cost of proper coverage is a small fraction of the cost of replacing a container of damaged equipment out of your own pocket.